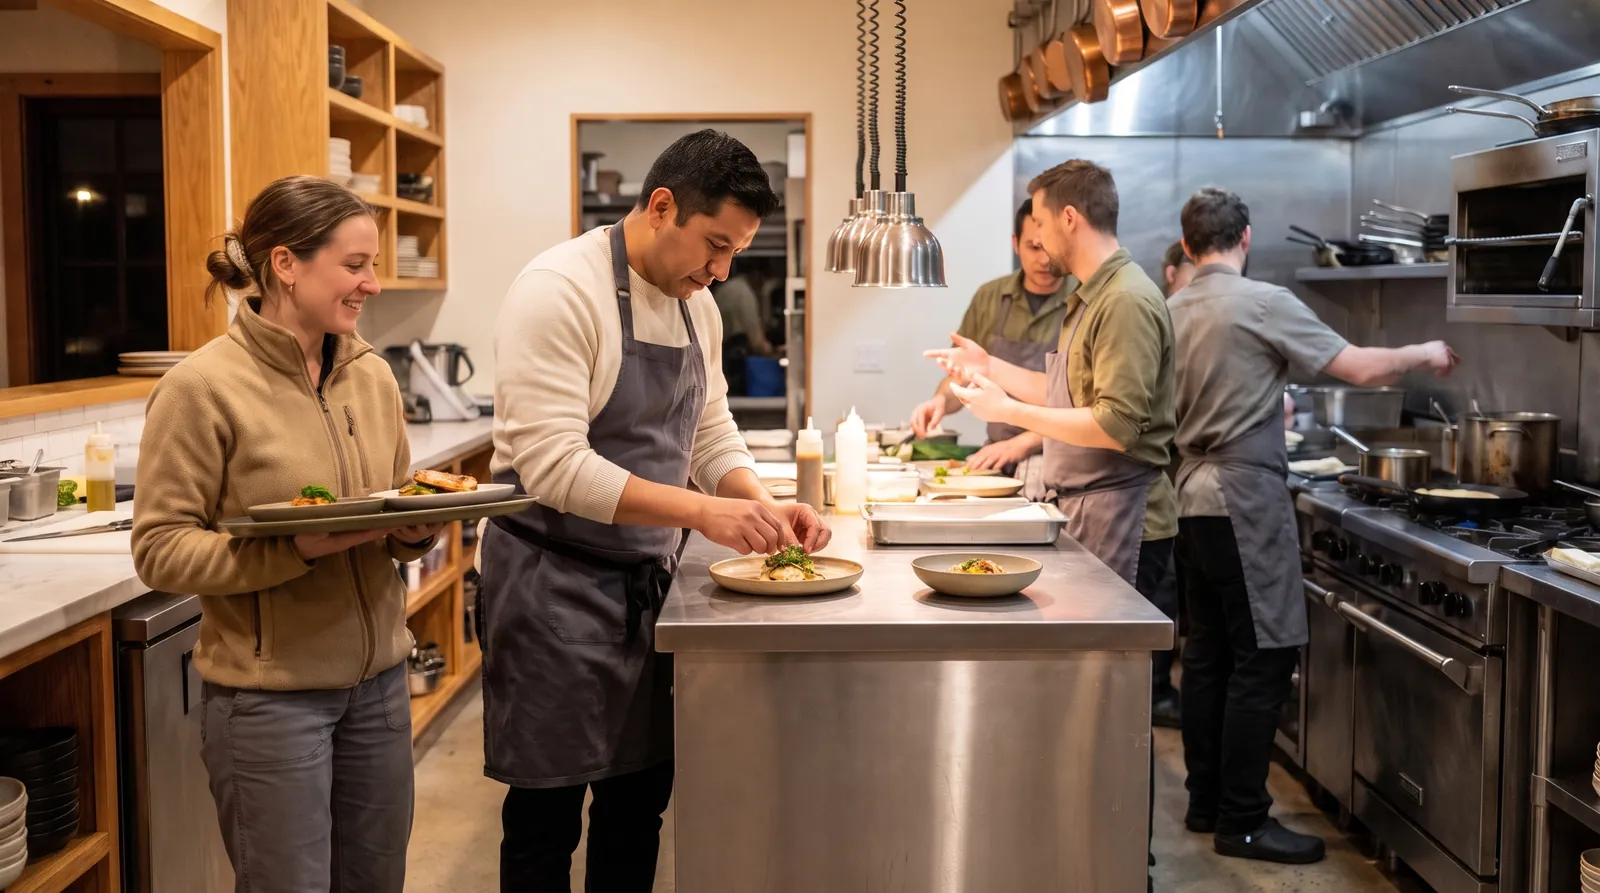
A restaurant takes money in every day and pays it out on a dozen different schedules. Distributors want payment weekly or on delivery. Payroll runs every week or two. Rent is due on the first, the hood cleaning comes quarterly, and the walk-in cooler picks its own day to quit.
Well-run restaurants plan for that rhythm, and the right financing fits it. Each kind below does a different job, and a growing restaurant may use several of them over the years.
What a restaurant’s statements show
Restaurants deposit card sales almost every day, so a few months of bank statements tell a clear story. They show weekday and weekend patterns, the seasons, and the lift from a new menu or a reopened patio. Lenders that lend on cash flow read those deposits closely. Banks tend to weigh other things more heavily, such as years in business, collateral and the length of your lease.
What the statements can’t show is what’s coming. A catering contract that starts next month, or a second dining room opening in spring, is worth a sentence when you apply.
Equipment financing for the kitchen
Ovens, ranges, walk-in coolers, dish machines, hoods, ice machines and point-of-sale hardware all earn their keep for years, so it makes sense to pay for them over years. With equipment financing, the equipment secures the financing, terms often follow its working life, and used equipment frequently qualifies. You’ll need a quote from the seller.
For example, a pizzeria adds a second deck oven before football season, when Friday orders back up out the door. Spread over the oven’s working life, the payment comes out of the extra pies it makes.
The same goes for a sudden replacement. When a compressor gives out on a Saturday, financing the new cooler keeps the cash you set aside for food and payroll where you planned it.
A line of credit for the swings
A business line of credit is a limit you draw on, repay and draw again, paying only on what you’ve drawn. Restaurants use it for:
- Stocking up ahead of the holidays or a festival weekend
- Covering a week when food costs jump
- Payroll through a slower stretch, such as the weeks after New Year’s
- Supplies for a catering job before the client pays
Open a line while business is strong, so it’s in place when one of those weeks arrives.
Term loans for renovations and new locations
A term loan is one sum up front, with fixed payments over a set term. It suits a project with a clear price and a lasting return:
- A remodel or a new bar
- A patio or more seats
- A second location
- Buying out a partner
A lender financing a build-out may ask how long your lease runs, since the improvements stay with the space. A lease that runs longer than the loan answers that question up front.
Working capital for a short gap with a clear end
Working capital, often structured as a cash advance, is a lump sum repaid out of your sales over a short term, usually through small daily or weekly payments. Daily card deposits make a restaurant’s business easy to read, so a request can move quickly.
Use it for something with a defined payoff, such as a supplier’s price on a large order or the stretch between one busy season and the next. Before you sign, ask for the total you’ll repay in dollars, and check that the daily or weekly payment still fits your slowest days.
Bridge capital for buying a location on a deadline
If you’re buying a restaurant or a building and the seller’s closing date comes before your long-term loan is ready, bridge capital can carry you to the closing. The long-term loan pays it off when it funds. A liquor license transfer, the landlord’s consent or an inspection can each move a closing date, so ask what an extension costs before you sign. See what a bridge loan is for how that payoff works.
Invoice financing for catering and wholesale
Most restaurant revenue is paid at the table, with nothing to invoice. Catering is different. A restaurant that caters for corporate clients, or sells sauces or baked goods to grocers on 30-day terms, has invoices waiting to be paid, and invoice financing can turn them into cash. See invoice factoring and financing, explained.
Match the money to the need
- New or replacement kitchen equipment: equipment financing
- Holiday stock-ups and payroll swings: a line of credit
- A remodel, a patio or a second location: a term loan
- A short gap with a clear end, or a quick opportunity: working capital
- A purchase that has to close before long-term financing: bridge capital
- Corporate catering and wholesale invoices: invoice financing
What lenders look at for restaurants
- Monthly deposits, and how steady they are through the seasons
- Time in business and your credit
- What you already pay on existing financing
- Overdrafts or negative balances on your statements
- For a build-out, the time left on your lease
Apply after your strong months show on your statements, and add a note about your seasons if they’re pronounced. Seasonal business financing covers that timing in more detail, and what lenders weigh covers the rest.
Before you sign any offer
- Ask for the total you’ll repay in dollars, next to the amount you receive.
- Check how often payments are taken. A daily payment set against a Monday’s sales feels different from the same payment set against a Saturday’s.
- Ask what’s pledged. A blanket lien on the restaurant’s assets can make later equipment financing harder to arrange, as secured vs. unsecured business loans explains.
- Find out who signs a personal guarantee, and what it covers.
- Ask whether paying early lowers the cost.
Find the right fit for your restaurant
See financing for restaurants and apply from that page. Applying takes a few minutes and won’t affect your credit score. We’ll review your application and match you with the options that fit.