HVAC financing
Get $5,000 to $10 million to buy equipment, cover payroll through slow seasons or take on larger commercial installs, funded in as little as 24 hours.
- No collateral required
- Same-day decisions
- No hard credit pull
Simple, fast and clear.
- $5K–$10M
- Funding amounts
- 500+
- Minimum credit score
- Same day
- Decisions
- 24hours
- Fastest funding
HVAC financing options at a glance.
Service calls pay on the spot, commercial jobs pay on terms, and your busy seasons depend on the weather. What you’re paying for, and when the money comes back, decide which option fits.
Small Business Term Loans
- Best for
- A second location, a new service area or buying a retiring owner’s customers
- Repayment term
- 6 to 48 months
- Min. credit score
- 500+
Business Line of Credit
- Best for
- Stocking equipment before peak season and technician pay through the slower months
- Repayment term
- Revolving: repay and draw again
- Min. credit score
- 500+
Equipment Financing
- Best for
- Service vans, recovery machines and the tools newer refrigerants call for
- Repayment term
- 2 to 5 years
- Min. credit score
- 500+
Invoice Financing
- Best for
- Commercial jobs and property managers paying on 30- to 60-day terms
- Repayment term
- Per invoice, when your customer pays
- Min. credit score
- 500+
Working Capital
- Best for
- A large commercial install, or a slow spring before a busy summer
- Repayment term
- 3 to 24 months
- Min. credit score
- 500+
How HVAC financing works.
HVAC work is seasonal. Most calls come in summer and winter, but the equipment, the vans and the trained technicians have to be in place before then, and commercial jobs bill on terms long after the system is installed. Financing covers the time between paying for the work and getting paid for it.
You apply online in minutes. Our team reviews your application and brings you the options that fit your business. We look at your revenue, deposits and time in business, not just your credit score, and your statements show your busy and slow seasons as well as your totals.
Read more
Time it to the season. A line of credit opened after a strong stretch is there to draw on through the slower months and the weeks before the next peak. Vans and tools suit equipment financing, and commercial invoices suit invoice financing.
What we look at. Your recent deposits, your time in business and your credit. Maintenance agreements are steady revenue in a seasonal trade, so tell us how many you have.
What it costs. Prices vary by lender and by business. Compare offers by what you’ll receive, each payment and the total you’ll repay, all in dollars.
See how we stack up.
| Traditional Bank | Typical Online Lender | ||
|---|---|---|---|
| Decision speed | Same-day | 2-8 weeks | 1-3 days |
| Credit check | Soft pull only | Hard inquiry | Often a hard pull |
| Min. credit score | 500+ | 680+ | Varies |
| How they decide | Revenue + 50 factors, human review | Tax returns, financials | Algorithm only |
| Who you work with | One dedicated advisor | Loan committee | Call center or portal |
| Collateral | None required | Often required | Sometimes |
| Funding range | $5K-$10M | $50K+ minimum | Varies |
| Apply NowApplying won’t affect your credit score. |
HVAC financing for every situation.
Each season brings different costs.
A slow spring before a busy summer
Your best technicians are worth keeping through the slower months. A line of credit covers payroll until the calls pick up, and is repaid as they do.
Adding a service van
A new technician needs a stocked van on the first day. Equipment financing spreads the cost of the van over the years you use it.
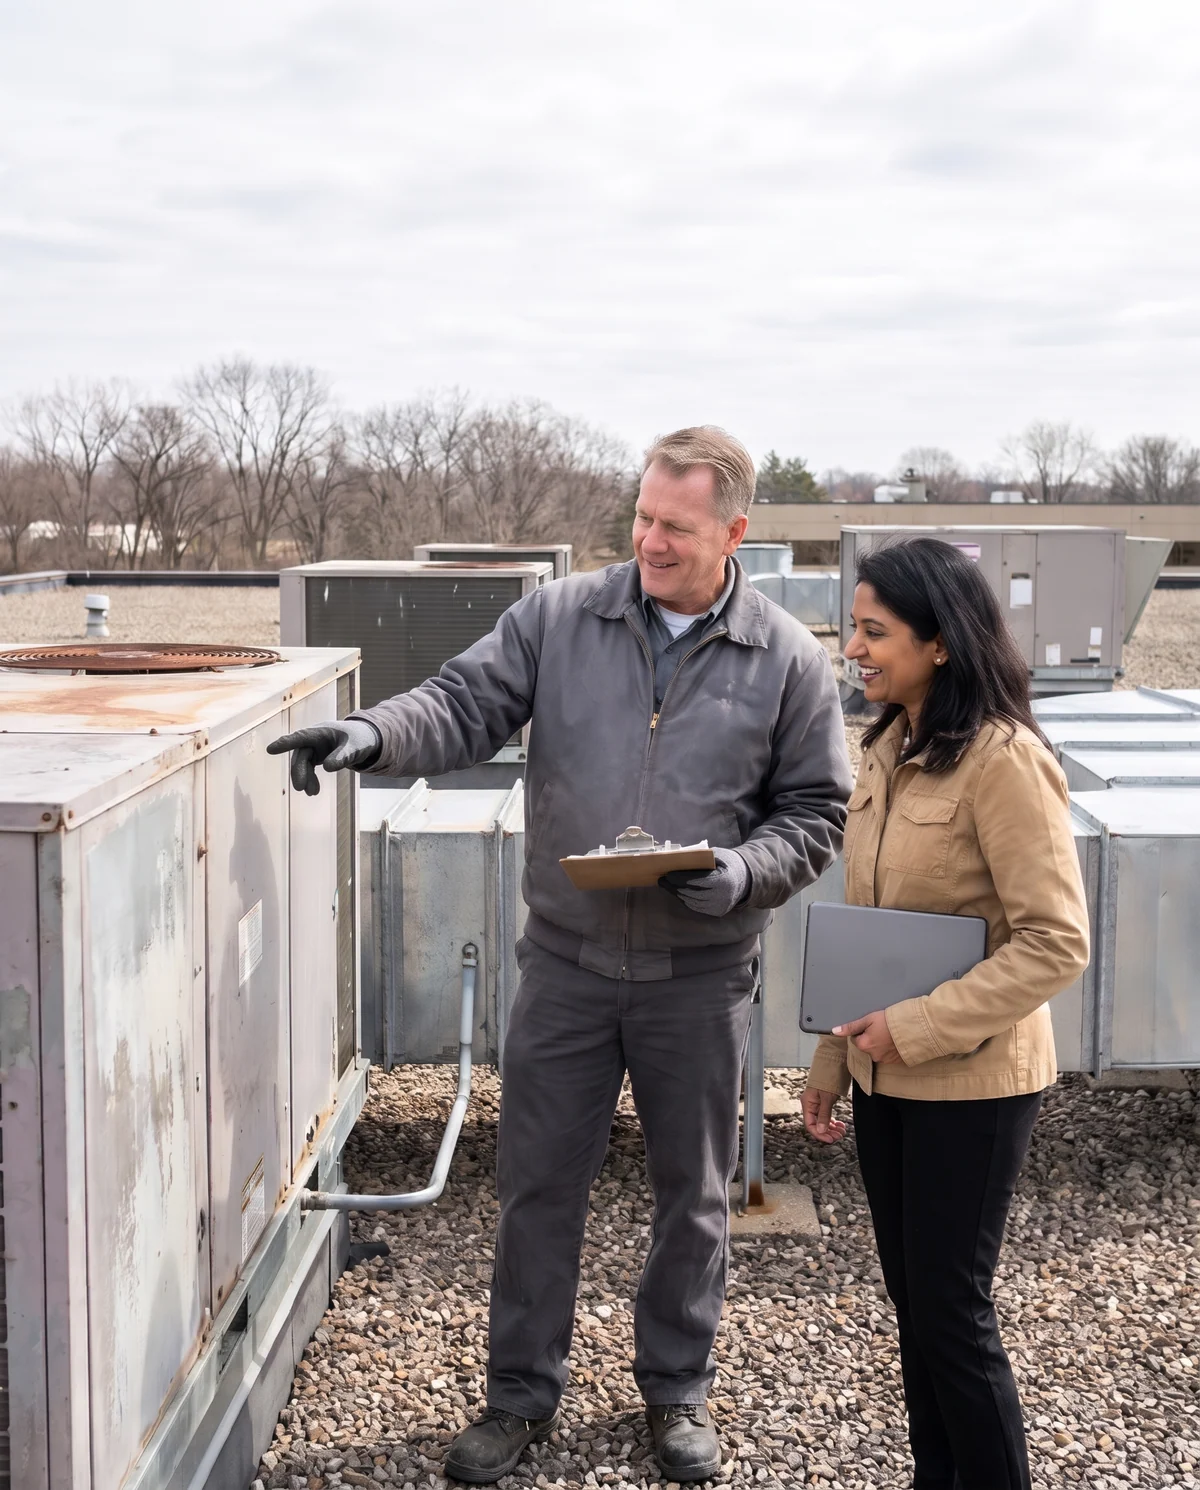
A property manager wants every rooftop unit replaced before summer. Working capital buys the equipment now, and invoice financing covers the wait once you’ve billed.
What HVAC contractors use financing for.
Payroll through slow seasons
Keeping your best technicians on staff through spring and fall, so they’re with you for peak season.
Equipment stocked before peak season
Condensers, furnaces and heat pumps bought before peak season, to avoid back orders during it.
Service vans
Another van, fitted out and stocked, for the next technician you hire.
Tools and training
Recovery machines, leak detectors and certifications as refrigerants and codes change.
Commercial installs
Materials and labor for jobs that bill on terms, so you can bid on larger ones.
A new service area
A second shop, or technicians based closer to new customers.
All you need to qualify.
We look at more than your credit score, including your revenue history, deposit consistency and time in business. An HVAC company with strong cash flow may qualify even with imperfect credit.
- No collateral
- No hard credit pull
- No upfront fees
- 500+
- Minimum credit score
- 6+months
- In business
- $150K+
- Yearly revenue
- 4months
- Of bank statements
Three steps to your funding.
- 1
Apply online
Fill in our short application in a few minutes. A few basics about your business and what you need, with no stack of paperwork to get started.
- 2
Get your options
Our team reviews your application and brings you the options that fit your business. We look at revenue, deposits and time in business, not only your credit score.
- 3
Receive your funds
Once you’re approved and the documents are signed, the funds can be in your business bank account in as little as 24 hours.
Frequently asked questions.
Is Noya Funding a lender?
Noya Funding is a business funding broker. We work with a wide network of lenders: our team reviews your application, matches you with the options that fit your business and stays with you through funding.
Does applying affect my credit score?
No. There’s no hard credit pull to apply, so applying won’t affect your credit score.
How do you look at an HVAC company’s cash flow?
Through your business bank statements, so a summer peak and a quieter spring show up side by side. Service agreements are steady revenue in a seasonal trade, so tell us how many you have.
Our slow months are spring and fall. When should we apply?
After a strong stretch, while those deposits are on your recent statements. A line of credit opened then is ready to draw on through the quieter months, and you pay interest only on what you draw.
Can I finance a service van?
Yes. Equipment financing covers work vans, new or used, up to 90% of their value, with the van itself as the collateral. You’ll need a quote from the dealer or the upfitter.
How much can an HVAC business get?
From $5,000 to $10 million. The amount rests on your monthly revenue, your time in business and your credit, and on what the money is for: equipment financing covers up to 90% of a van’s value, and invoice financing up to 90% of what a commercial customer owes.
Which states do you work in?
Every state except Texas, Virginia, Connecticut and Missouri, where we can’t take requests yet.
Ready to get funded?
Apply online in minutes. No collateral, no hard credit pull and no obligation.