Roofing business financing
Get $5,000 to $10 million to buy materials in bulk, hire seasonal crews or bridge insurance payout delays, funded in as little as 24 hours.
- No collateral required
- Same-day decisions
- No hard credit pull
Simple, fast and clear.
- $5K–$10M
- Funding amounts
- 500+
- Minimum credit score
- Same day
- Decisions
- 24hours
- Fastest funding
Roofing financing options at a glance.
Home jobs are often paid by an insurer, and commercial jobs by a general contractor. The right option depends on what you’re paying for and who you’re waiting on.
Small Business Term Loans
- Best for
- Materials bought by the truckload, a storage yard or a second crew
- Repayment term
- 6 to 48 months
- Min. credit score
- 500+
Business Line of Credit
- Best for
- Materials and crew pay while insurance claims and supplements are settled
- Repayment term
- Revolving: repay and draw again
- Min. credit score
- 500+
Equipment Financing
- Best for
- Dump trailers, material lifts, trucks and compressors
- Repayment term
- 2 to 5 years
- Min. credit score
- 500+
Invoice Financing
- Best for
- Invoices to general contractors and commercial owners on 30- to 60-day terms
- Repayment term
- Per invoice, when your customer pays
- Min. credit score
- 500+
Working Capital
- Best for
- A busy storm season, or one large job that bills at the end
- Repayment term
- 3 to 24 months
- Min. credit score
- 500+
How roofing business financing works.
On a roofing job, costs come before payment. You buy materials and pay the crew to tear off and install, then wait on the homeowner’s insurer, which often pays in two parts, the second only once the roof is finished. Commercial work waits on the general contractor instead. Financing covers the time in between.
You apply online in minutes. Our team reviews your application and brings you the options that fit your business. We look at your revenue, deposits and time in business, not just your credit score.
Read more
Choosing the right option. A trailer or a lift suits equipment financing. Materials and crews ahead of claim payments suit a line of credit or working capital. Invoices to general contractors and commercial owners suit invoice financing.
What we look at. Your recent deposits, your time in business and your credit. If your work follows storms, tell us; a list of signed jobs and the insurance payments still to come explains the timing.
What it costs. Prices vary by lender and by business. Compare offers by what you’ll receive, each payment and the total you’ll repay, in dollars, against what the jobs it pays for bring in.
See how we stack up.
| Traditional Bank | Typical Online Lender | ||
|---|---|---|---|
| Decision speed | Same-day | 2-8 weeks | 1-3 days |
| Credit check | Soft pull only | Hard inquiry | Often a hard pull |
| Min. credit score | 500+ | 680+ | Varies |
| How they decide | Revenue + 50 factors, human review | Tax returns, financials | Algorithm only |
| Who you work with | One dedicated advisor | Loan committee | Call center or portal |
| Collateral | None required | Often required | Sometimes |
| Funding range | $5K-$10M | $50K+ minimum | Varies |
| Apply NowApplying won’t affect your credit score. |
Roofing financing for every situation.
Roofing work follows the weather, and busy stretches need money up front.
After a hailstorm
Inspections turn into signed jobs within days. Working capital buys materials and adds crews while the demand lasts.
Waiting on the second insurance check
Many policies pay the last part of a claim only once the roof is finished. A line of credit covers your costs until then and is repaid when that check clears.
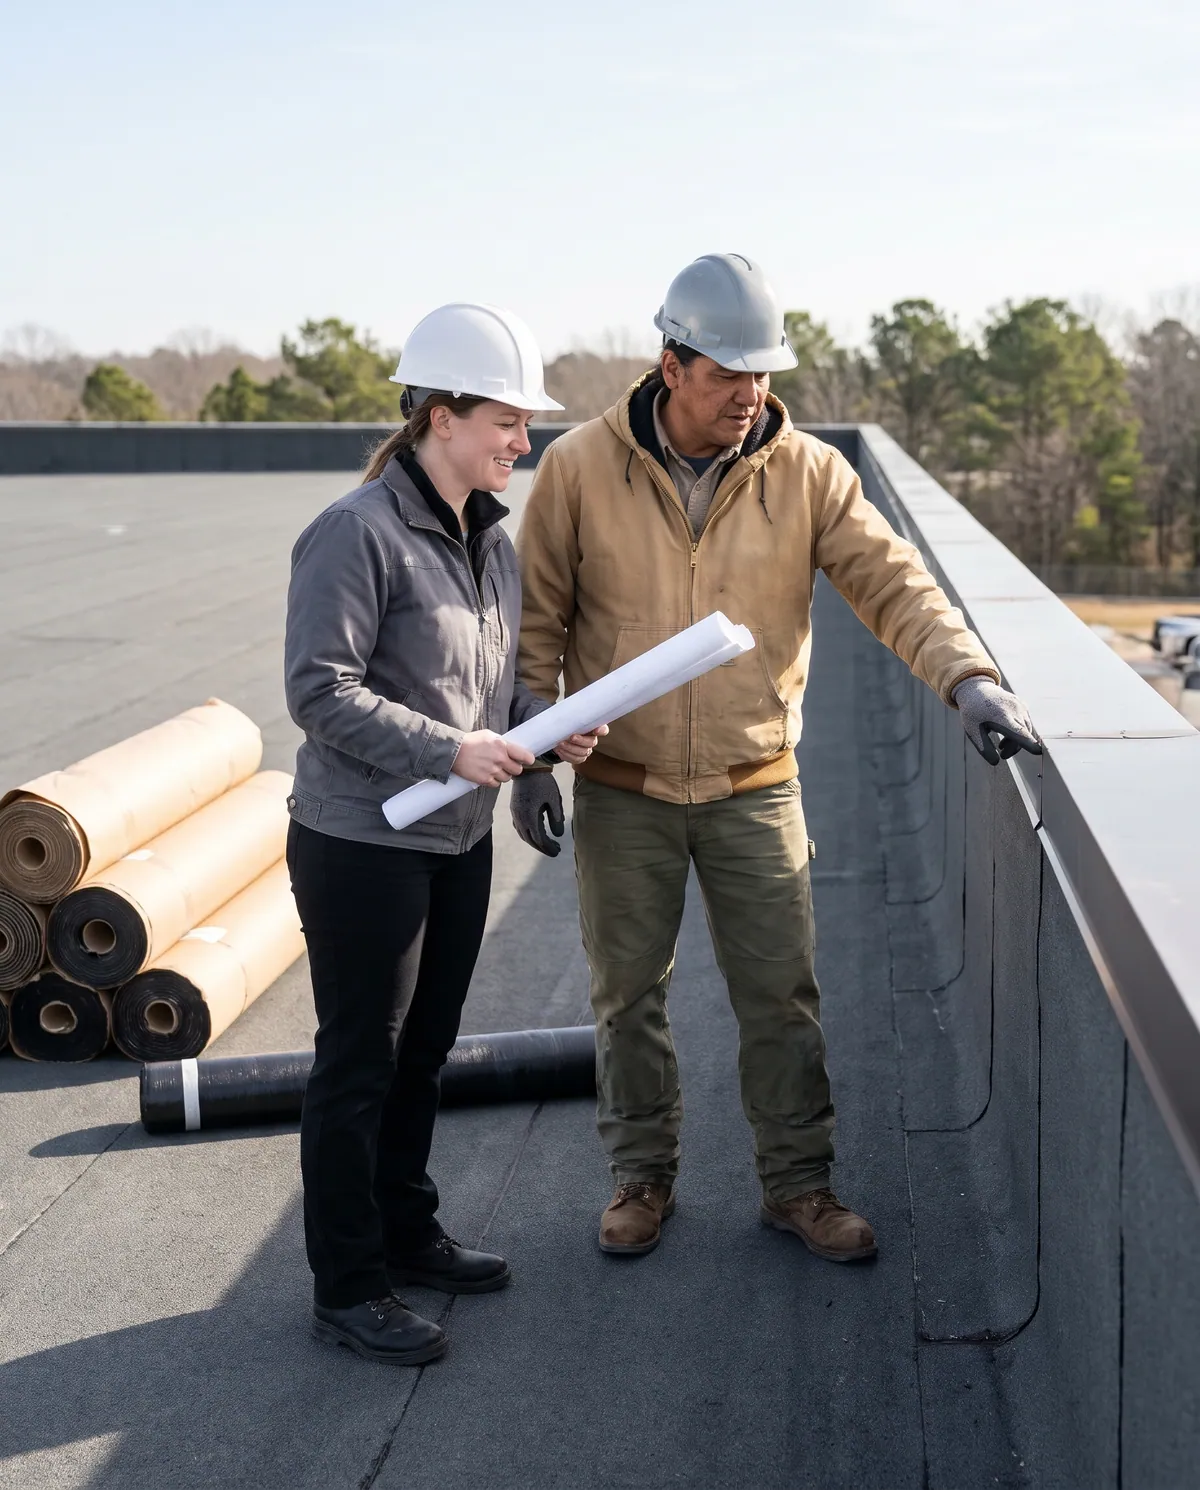
A warehouse roof is a much larger job than a house. Working capital covers the materials and the crane, and invoice financing covers the wait on the general contractor’s terms.
What roofing contractors use financing for.
Materials in bulk
Shingles, underlayment and metal bought by the truckload ahead of the season.
Seasonal crews
More crews when the work is there, paid on time every week.
Trucks, trailers and lifts
Dump trailers, material lifts and the trucks that pull them.
Insurance payout delays
The weeks between finishing a roof and the insurer’s final payment.
Commercial jobs
Materials and labor for flat roofs and larger contracts that bill on terms.
Equipment repairs
A compressor, a lift or a truck repaired before the next job starts.
All you need to qualify.
We look at more than your credit score, including your revenue history, deposit consistency and time in business. A roofing company with strong cash flow may qualify even with imperfect credit.
- No collateral
- No hard credit pull
- No upfront fees
- 500+
- Minimum credit score
- 6+months
- In business
- $150K+
- Yearly revenue
- 4months
- Of bank statements
Three steps to your funding.
- 1
Apply online
Fill in our short application in a few minutes. A few basics about your business and what you need, with no stack of paperwork to get started.
- 2
Get your options
Our team reviews your application and brings you the options that fit your business. We look at revenue, deposits and time in business, not only your credit score.
- 3
Receive your funds
Once you’re approved and the documents are signed, the funds can be in your business bank account in as little as 24 hours.
Frequently asked questions.
Is Noya Funding a lender?
Noya Funding is a business funding broker. We work with a wide network of lenders: our team reviews your application, matches you with the options that fit your business and stays with you through funding.
Does applying affect my credit score?
No. There’s no hard credit pull to apply, so applying won’t affect your credit score.
How do you look at a roofing company’s cash flow?
Through your business bank statements. Storm-driven work shows up as busy stretches and quieter ones, which is normal in this trade. A list of signed jobs and the insurance payments still to come explains what’s ahead.
Most of our work comes after storms. Does that count against us?
Storm-driven seasons are normal in roofing, and we read your busy months alongside your quiet ones.
Can I finance a dump trailer or a material lift?
Yes. Equipment financing covers trailers, lifts and trucks, new or used, up to 90% of their value, with the equipment itself as collateral. You’ll need a quote or a bill of sale from the seller.
How much can a roofing business get?
From $5,000 to $10 million. The amount rests on your monthly revenue, your time in business and your credit, and on what the money is for: equipment financing covers up to 90% of the equipment’s value, and invoice financing up to 90% of what a commercial customer owes.
Which states do you work in?
Every state except Texas, Virginia, Connecticut and Missouri, where we can’t take requests yet.
Ready to get funded?
Apply online in minutes. No collateral, no hard credit pull and no obligation.